TH
 EN
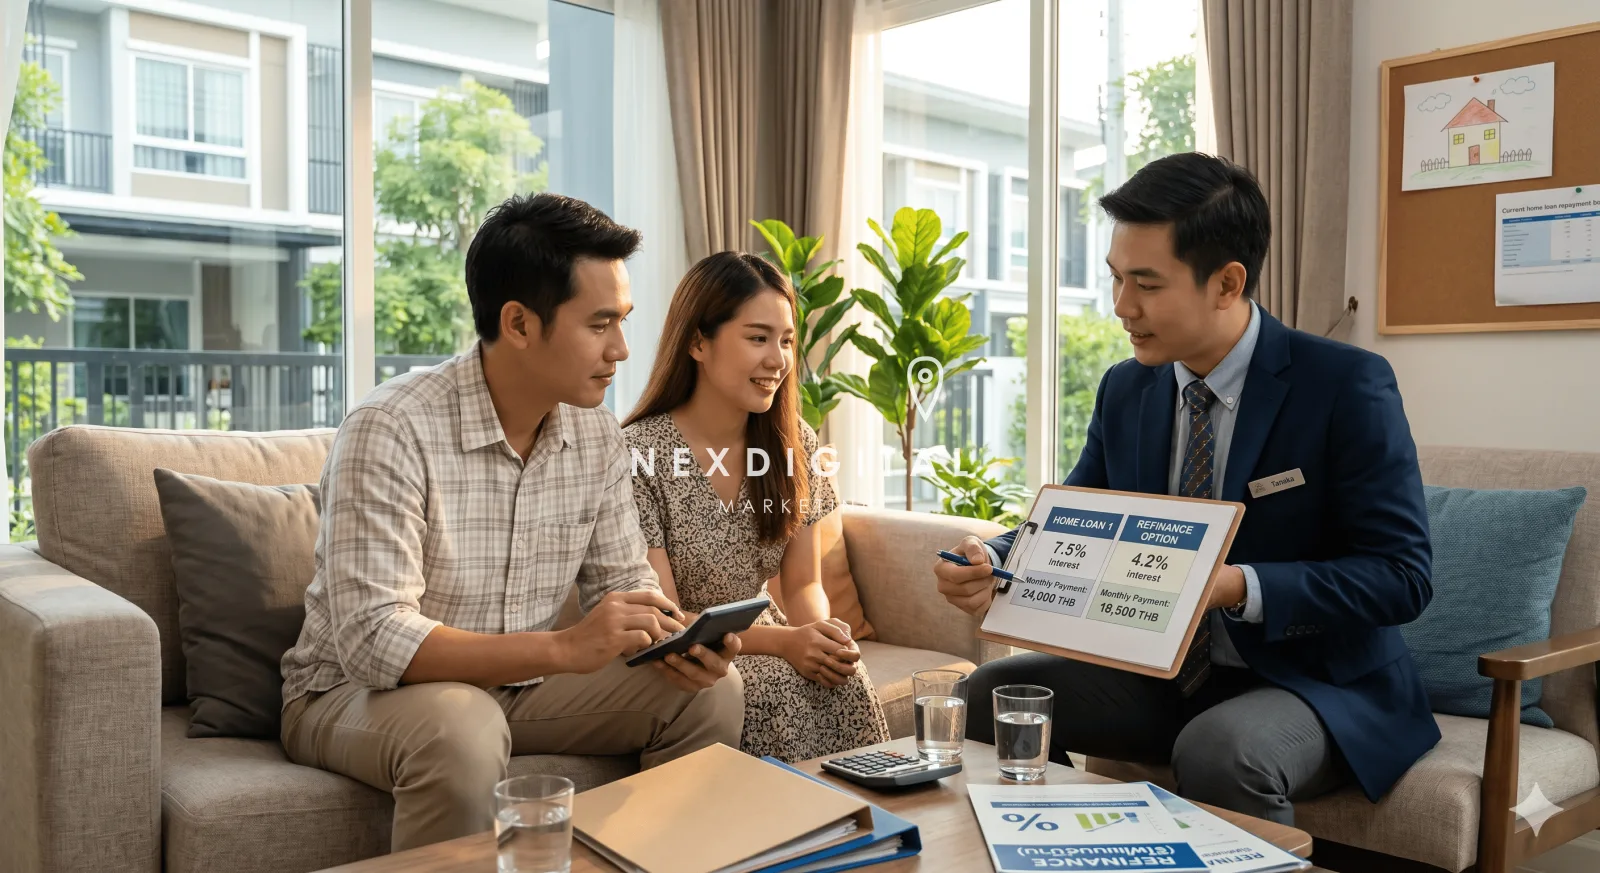
If you’re currently paying off a home or condo, you’ve probably experienced this at some point. During the first 2–3 years, the monthly payments may feel manageable and the interest rate looks attractive. But once you reach the fourth year, the monthly payment stays almost the same while barely reducing the principal.
This is something many homeowners eventually face. Low promotional interest rates on home loans usually apply only during the initial period. After that, the interest rate may increase based on each bank’s MRR or MLR. This is why “home loan refinancing” has become an important consideration for homeowners. By managing your interest rate wisely, you could potentially save hundreds of thousands of baht without having to earn any additional income.
What Is Home Loan Refinancing?
Simply put, “home loan refinancing” means transferring your home loan from your current bank to a new bank in order to get better terms, such as a lower interest rate, lower monthly payments, more manageable repayments, or additional financing. The new bank pays off your existing loan, and you then continue making payments to the new bank. In simple terms, it’s like switching mobile providers to get a better deal except this time, the balance could be worth millions of baht.
Why Do People Choose to Refinance Their Home Loans?
Here are some of the main reasons people choose to refinance their home loans.
1. To Reduce Home Loan Interest
This is one of the main reasons homeowners refinance. During the first three years, promotional interest rates are often around 2–3%, but once the promotional period ends, the rate may rise to 5–7% or even higher. This means more of your monthly payment may go toward interest rather than reducing the principal. Refinancing can help bring the interest rate back down and significantly reduce your long-term financial burden.
2. To Lower Monthly Payments
Life circumstances can change unexpectedly. Having children, changing jobs, starting a business, or taking on additional financial responsibilities can all increase your expenses. Refinancing may help reduce your monthly payments by adjusting the repayment period or securing a lower interest rate, giving you more financial flexibility.
3. To Pay Off the Home Loan Faster
Many people think refinancing means simply “extending the debt.” However, with the right planning, it can actually help you pay off your loan faster. When the interest rate is lower, more of each payment can go toward reducing the principal, allowing your outstanding balance to decrease faster.
4. To Get Additional Financing (Top-Up)
Some homeowners also use refinancing as an opportunity to apply for additional financing, such as for home renovations, extensions, paying off credit card debt, or investment purposes. The new bank will reassess the property’s value and determine whether additional financing can be offered.
So, When Is the Right Time to Refinance?
The most common answer is “after completing the first three years.” In general, home loan agreements may have a lock-in period of around three years. Refinancing before this period ends may result in an early repayment fee of around 3% of the outstanding loan balance, which may make refinancing less worthwhile. Therefore, a good time to start planning is around 1–2 months before the promotional interest rate expires. This gives you enough time to compare banks, prepare the required documents, submit your application, and complete the property valuation.
3 Signs That It’s Time to Refinance
1. Your Interest Rate Starts to Increase
If your monthly payments suddenly become more difficult to manage, or you notice that the interest charged on your statement has increased significantly, your low-interest promotional period may have ended. This could be a good time to start looking into refinancing.
2. You’ve Been Paying for Years, but the Principal Has Barely Decreased
Some homeowners have been making payments for 4–5 years, yet their outstanding balance has barely decreased. One common reason is a higher floating interest rate. Refinancing may allow more of each monthly payment to go toward reducing the principal.
3. You Want to Reduce Your Monthly Financial Burden
If your finances are currently tight or you want to improve your cash flow, refinancing may help restructure your loan and reduce your monthly financial burden.
What Costs Should You Check Before Refinancing?
Although refinancing can help reduce your interest costs, there are also expenses that should be taken into account, such as: New property valuation fee Mortgage registration fee Stamp duty Fire insurance premium MRTA premium (if applicable) Before making a decision, calculate carefully whether the interest savings are worth the refinancing costs. If the difference is only small, refinancing may not actually be worthwhile.
A Tip Many People Don’t Know
“Retention” may be an option that allows you to reduce your interest rate without switching banks. Before refinancing with a new bank, try negotiating with your existing bank and ask about a “retention” offer, which means requesting a lower interest rate while keeping your loan with the same bank.
The benefits include: No need to pay a new mortgage registration fee Less paperwork No need to go through the process of transferring your loan Sometimes, your existing bank may offer an interest rate that is just as competitive as refinancing with another bank, because they also want to retain good customers.
Conclusion: Home Loan Refinancing Is an Option Homeowners Shouldn’t Overlook
You don’t necessarily have to pay high interest on a home loan for the entire 20–30 year repayment period. By understanding when to refinance and planning ahead, you can potentially save a significant amount of money, reduce interest costs, lower your monthly payments, improve your cash flow, and even pay off your home sooner. Ultimately, being good at managing a home loan isn’t just about being able to make the payments it’s about knowing how to manage your interest costs wisely.
Interested in any of our projects or need advice on home loans? Contact the NEX Property team for a free consultation!